01
WHAT ACTUALLY HAPPENED
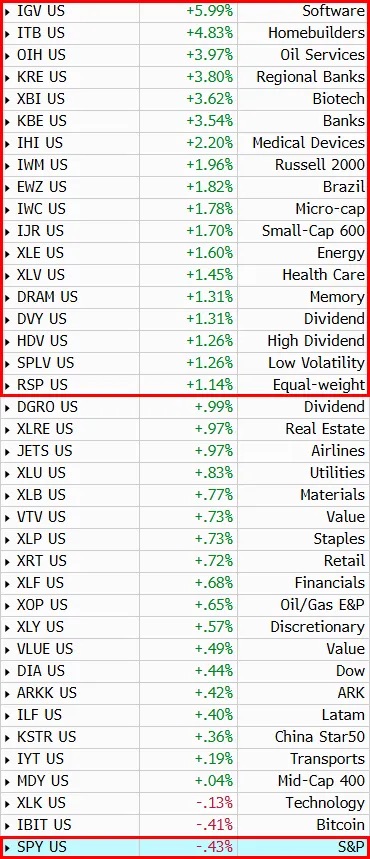
SPY -0.4% · QQQ -0.8% · Dow +0.4% · Equal-weight +1.1% · IWM +2.0%
· 66% of S&P names closed up. 7 of 11 sectors advanced. Leaders: Software and Homebuilders.
02
LEVERAGE RESET
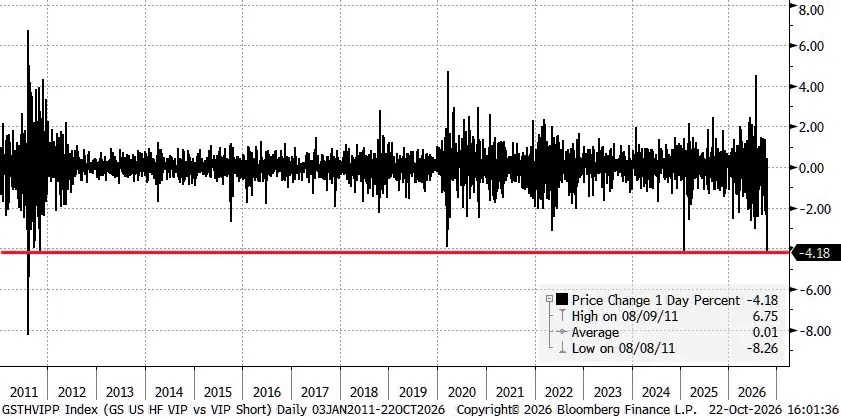
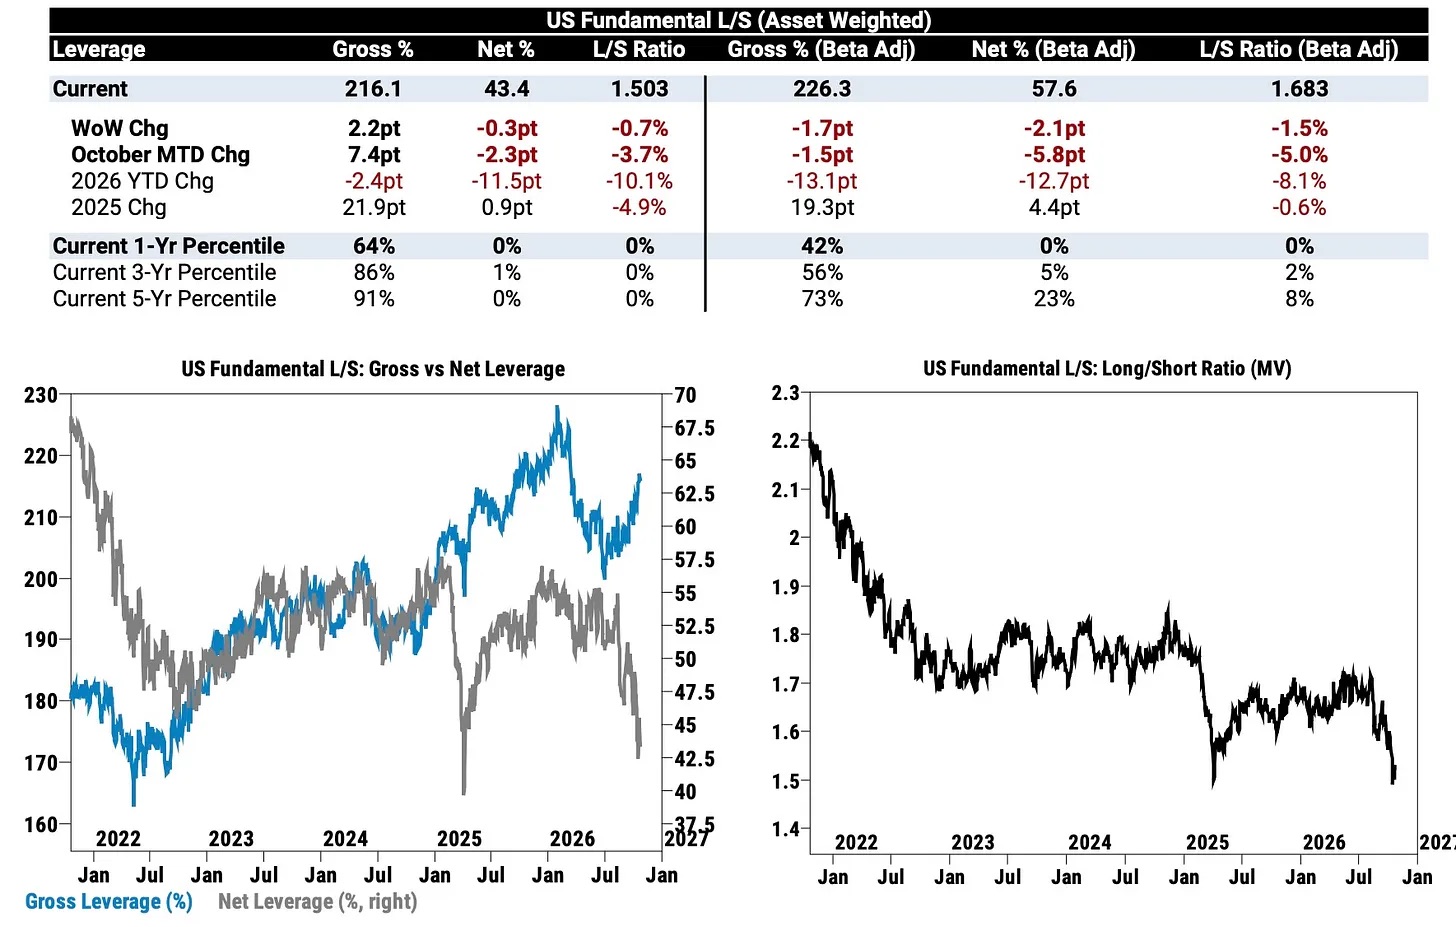
Thursday was the worst day for hedge fund books in 15 years. Goldman's "VIP longs vs most-shorted" pair dropped ~4.2% in one session, the biggest move since 2011, and is down 10.4% MTD.
Funds held tech longs and offset them with shorts elsewhere. The shorts squeezed, the longs lagged. Losses on both sides.
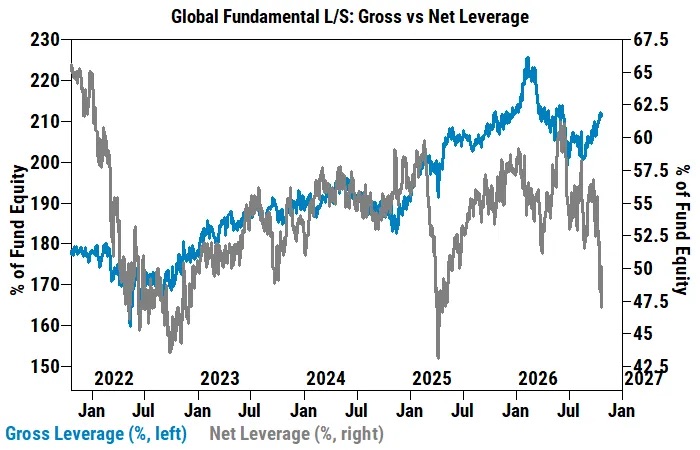
Global L/S net leverage has fallen toward the levels where the market bottomed in 2022 and 2025. US L/S net leverage is already below 2022 and nearly at the 2025 low.
Cash inflows are the fastest in years. Shorting spiked. This is a rare positioning washout, and historically it is the kind that shows up close to a tactical bottom.
03
RATES CONFIRM THE STRESS
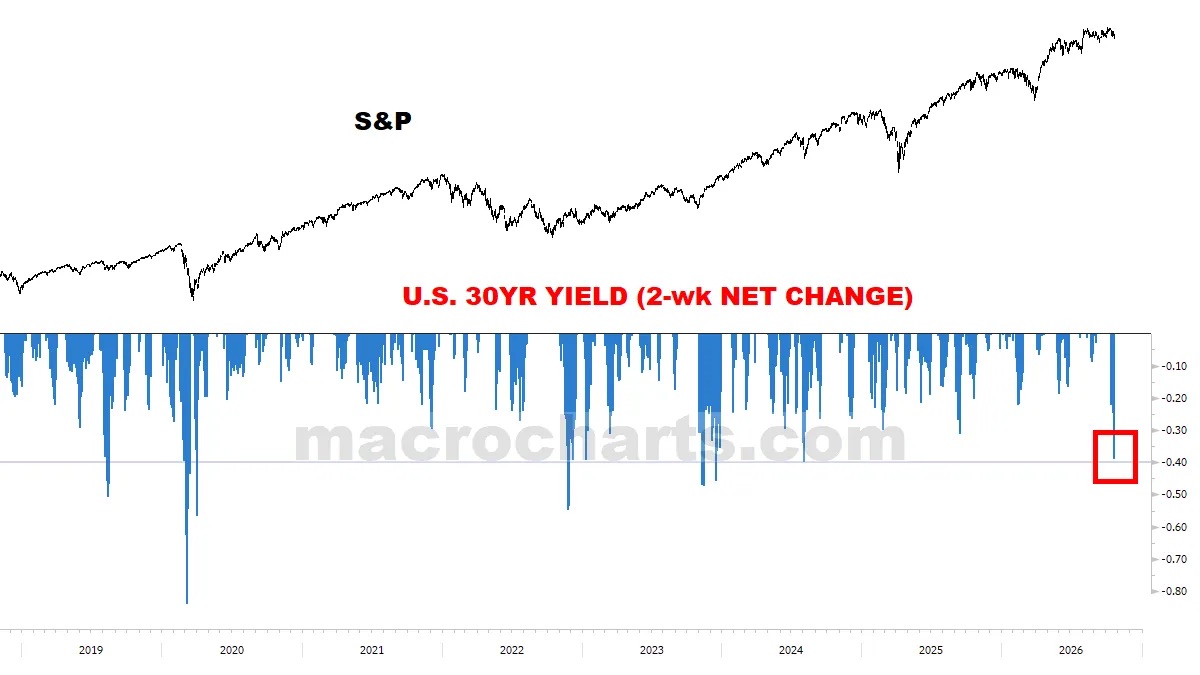
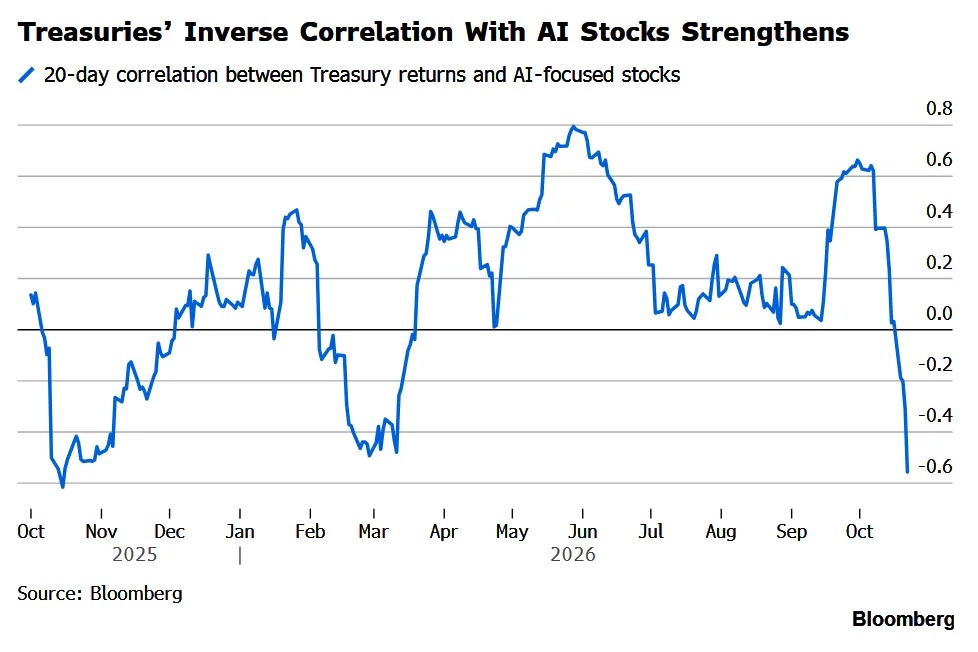
The 30Y yield posted one of its largest 2-week drops in years. Outside of 2008 and 2020, moves like this landed near panic lows in stocks. Tech and yields are tightly correlated right now, so a yield bounce would likely lift tech.
Metals were sold too. Daily sentiment: Gold 20, Silver 16, Platinum 10, Palladium 10. Looks like indiscriminate selling.
Bond Yields and Tech stocks are strongly correlated here. A bounce in Yields would likely see a recovery in Tech.
04
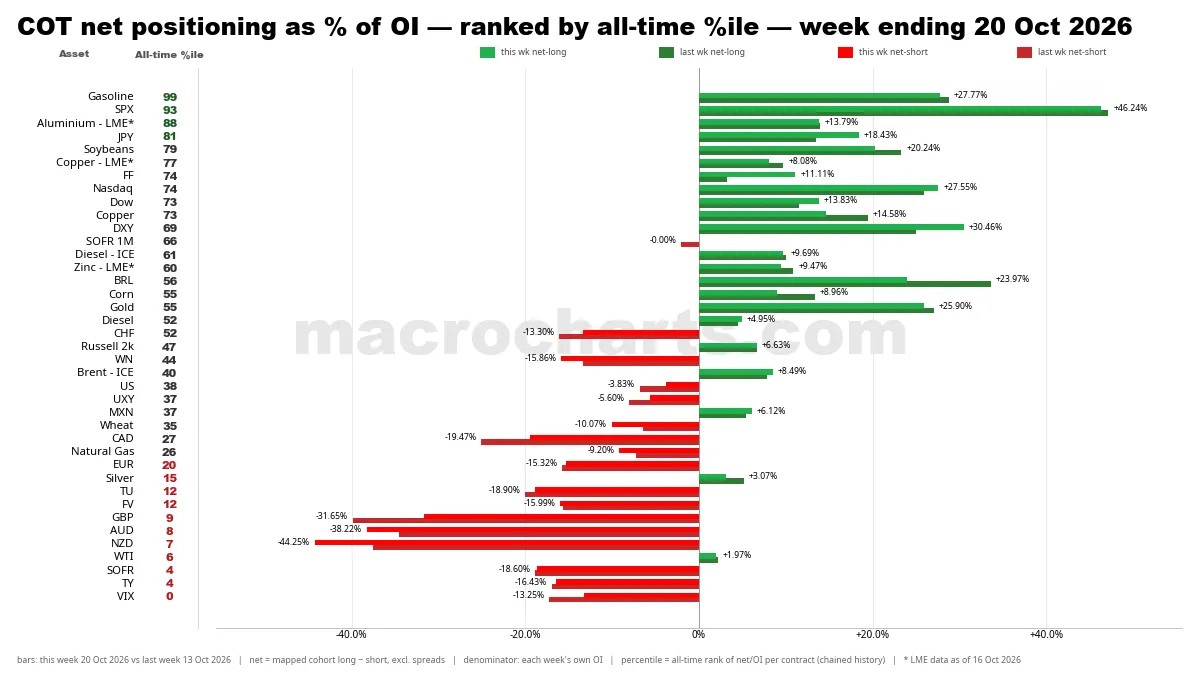
POSITIONING EXTREMES
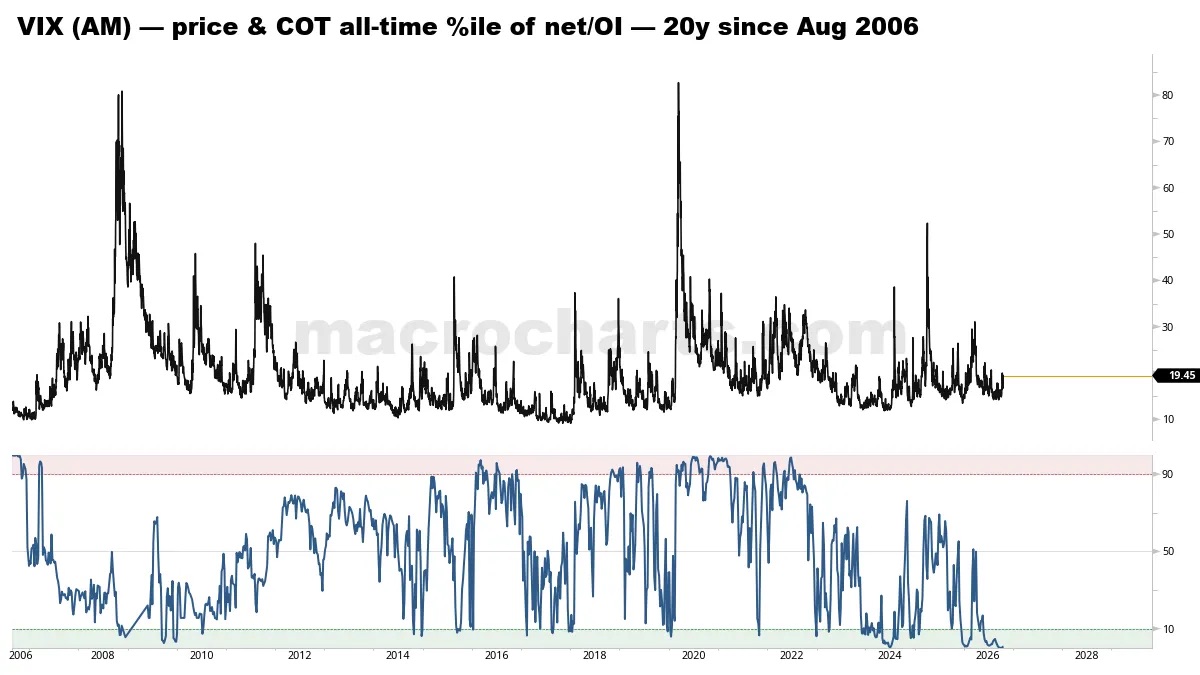
VIX: record short
Rates (TY, SOFR, FV, TU): very low
WTI: 6th percentile · Gasoline: 99th percentile
USD: 97th percentile · AUD, NZD: record short · EUR near 10y lows
Silver: 15th percentile
05
THE SCENARIO TO WATCH
NDX is down 8.1% over 13 days. In late 2025 the same setup was an 8.9% drop over 17 days, followed by a 9-10% rally. A repeat would mean one more leg lower this week (~28600, roughly 1% below current, undercutting the September low), then a run toward ~31300 …


The rest of this section and its charts are open to subscribers. The first 14 days are free.
Subscribe to read in full →06
Portfolio Update
No confirmed reversal yet, so we are waiting for proper conditions before opening new longs. Key macro models are close to buy signals, while midterm-year October seasonality, earnings, and the return of buybacks could support the market.
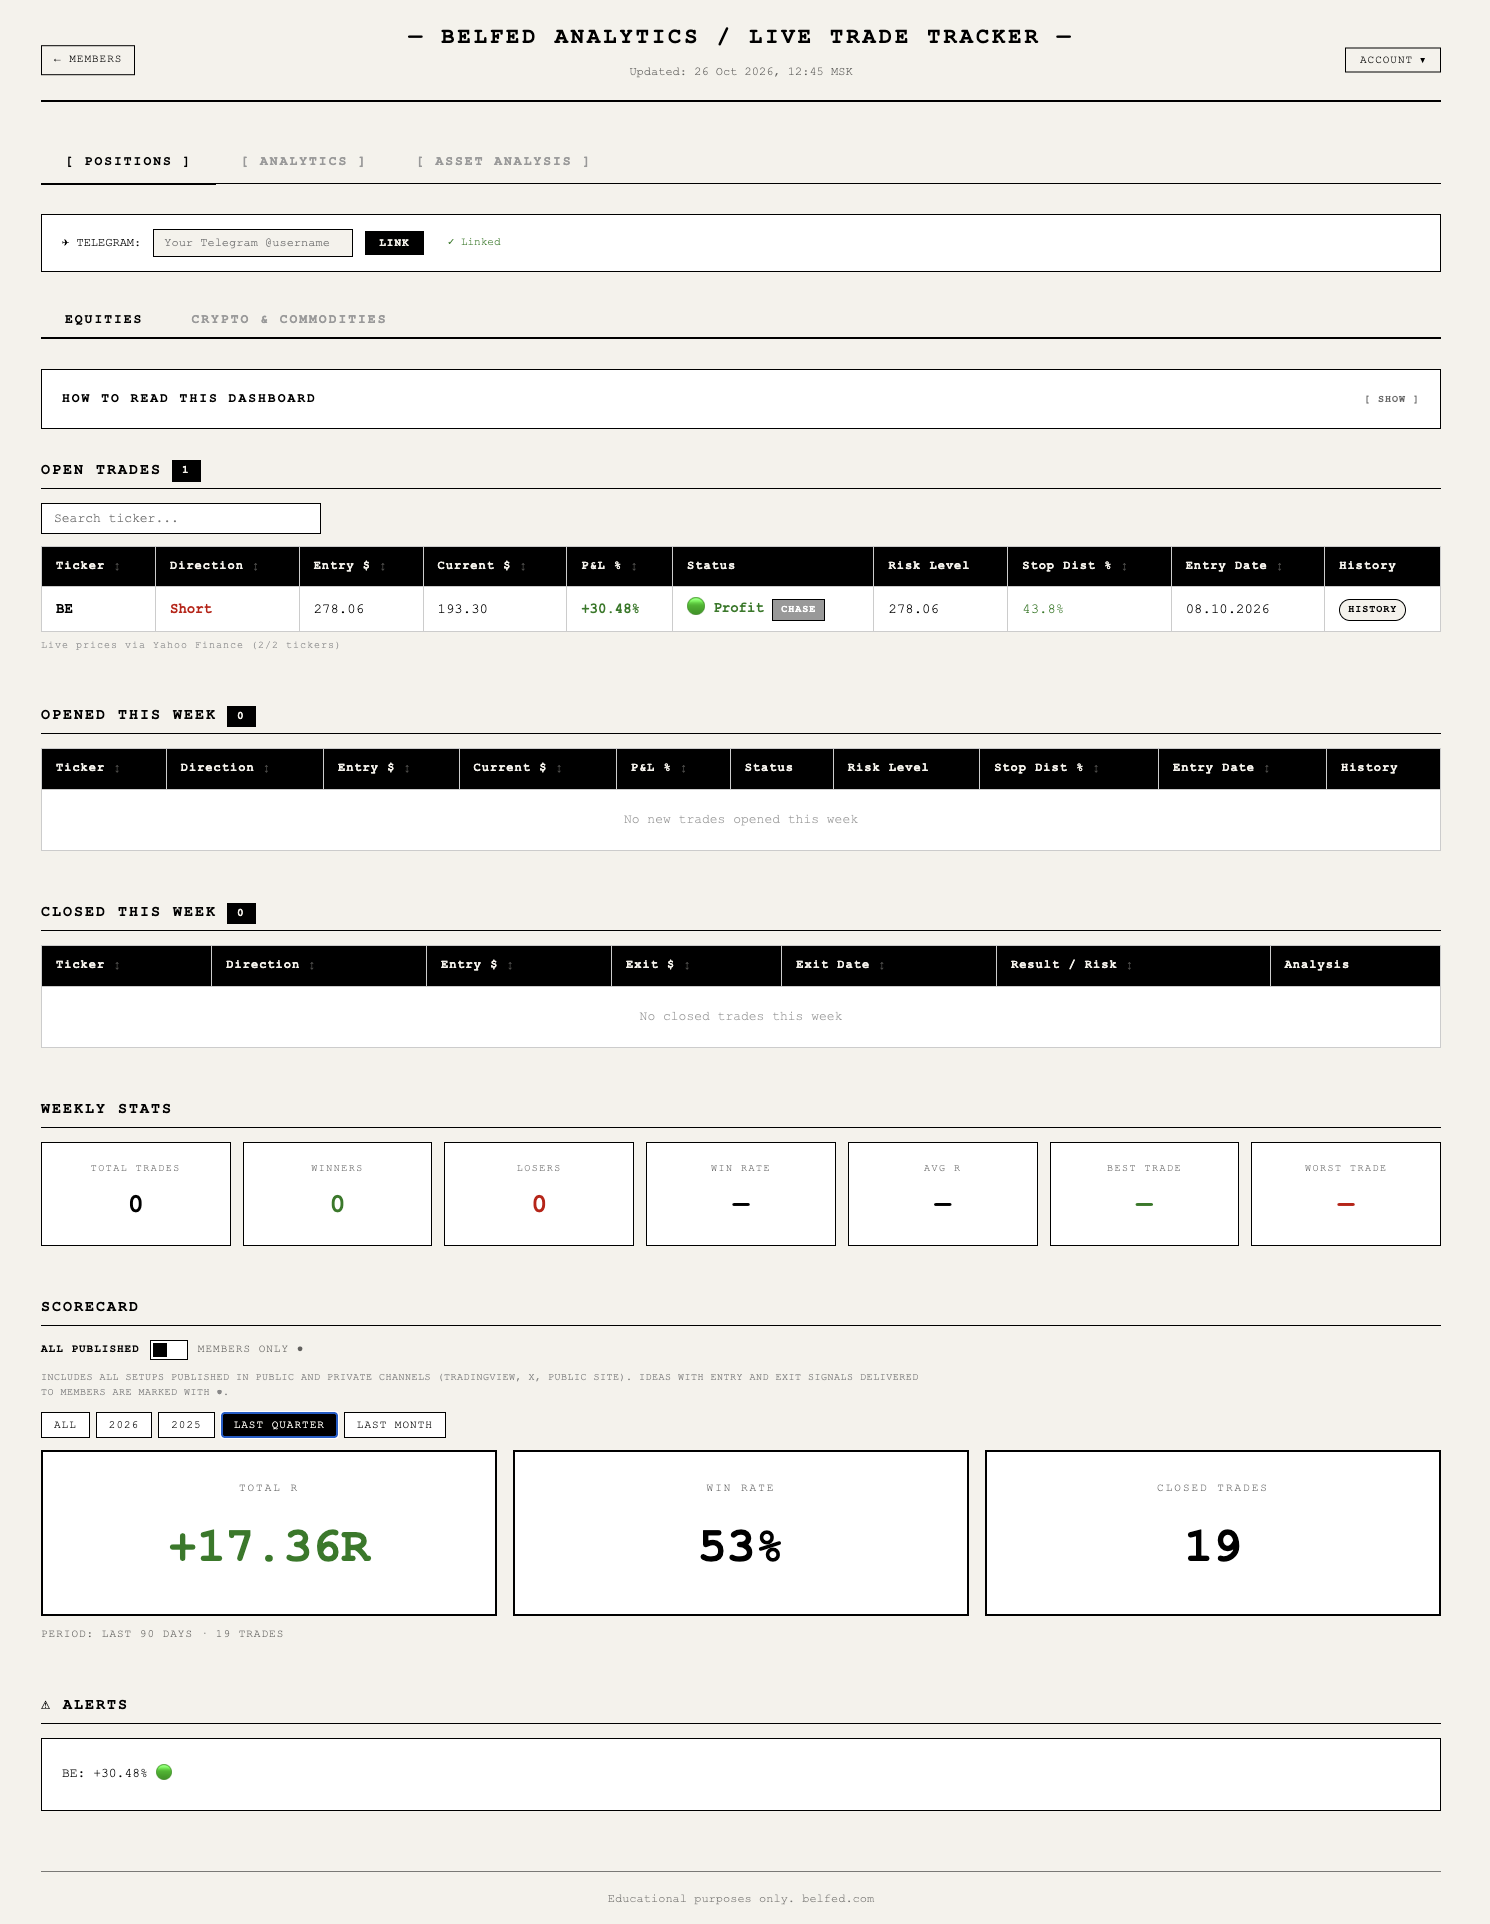
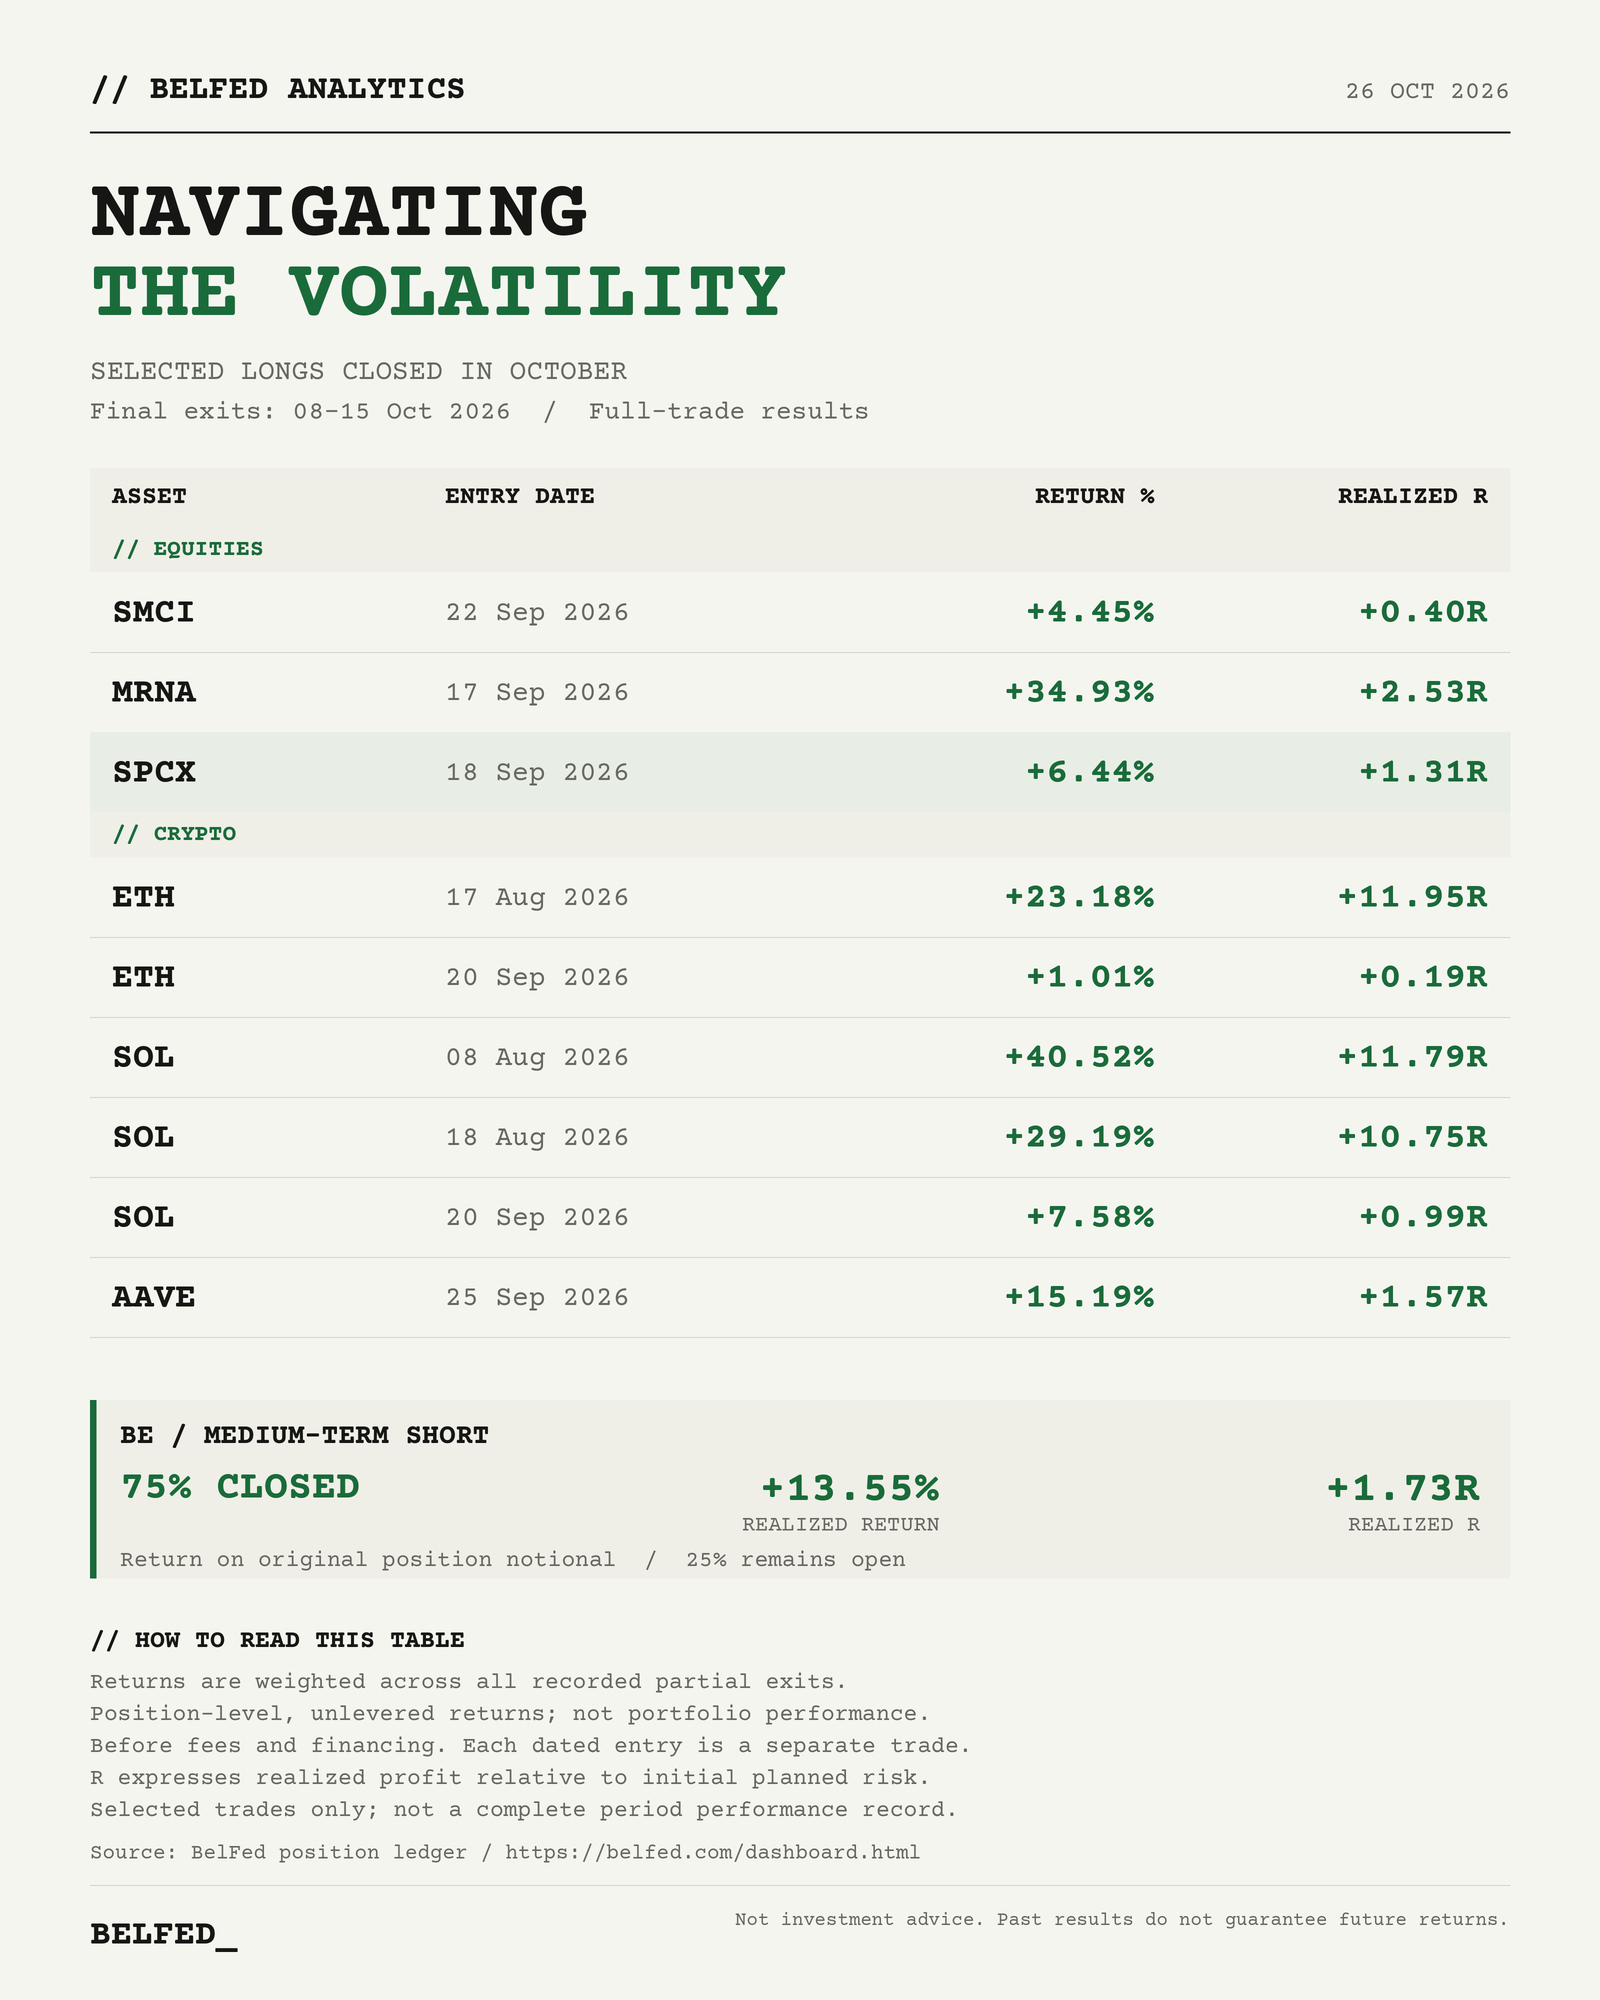
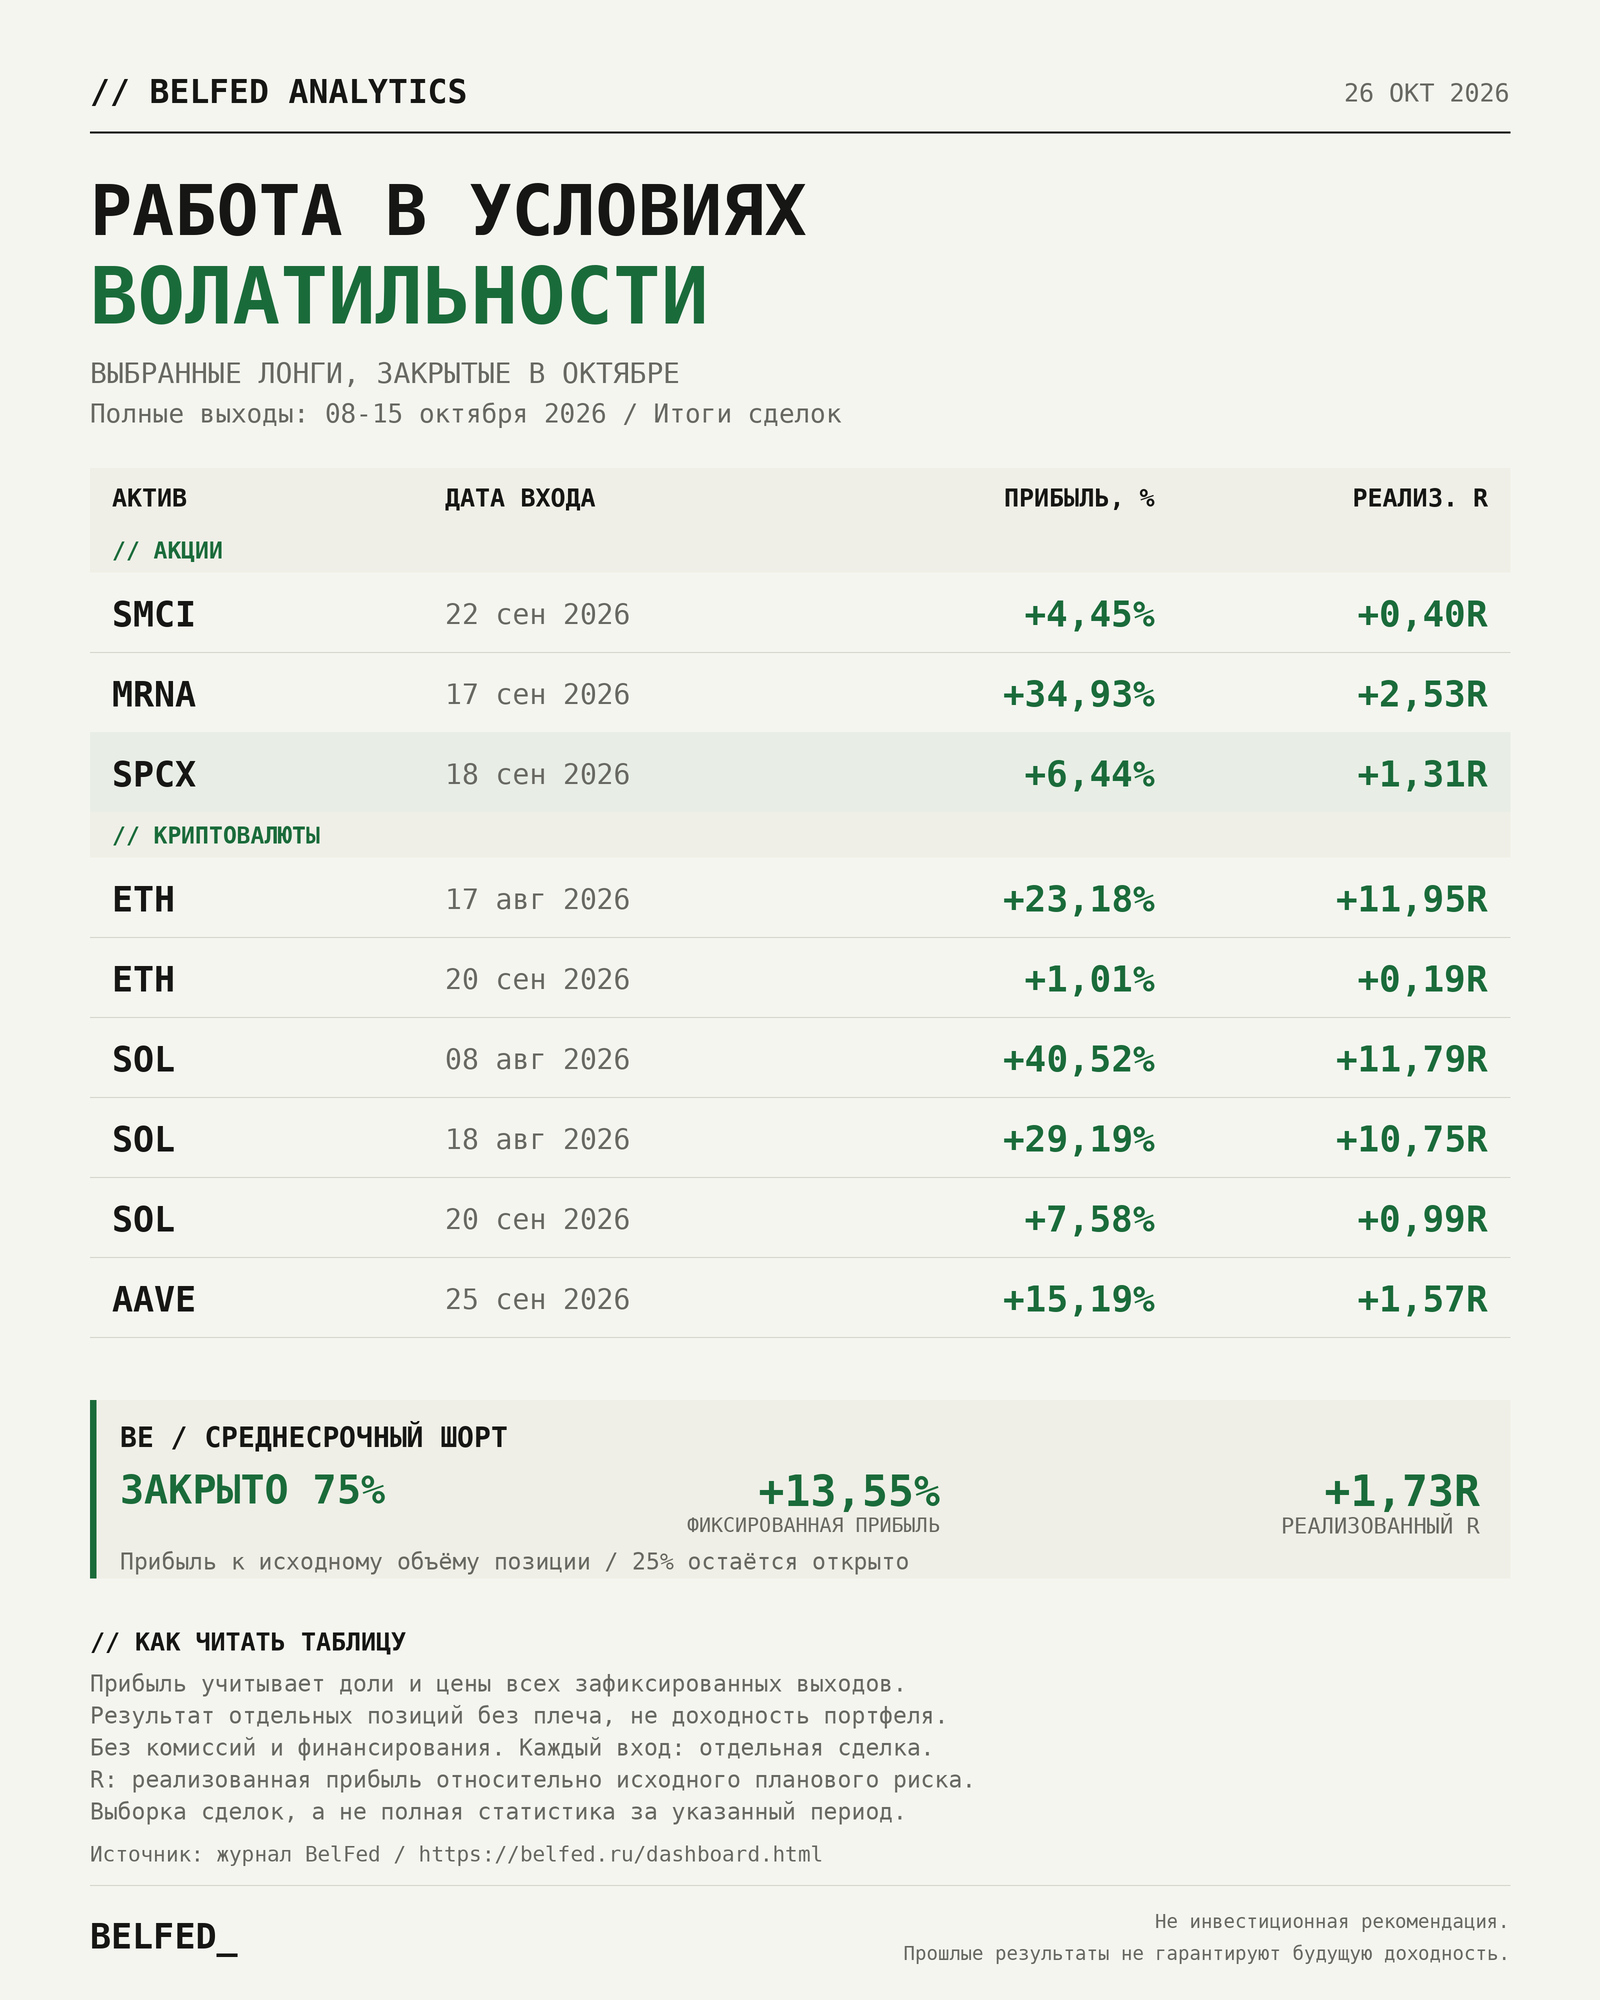
A defensive stance helped navigate the volatility: we closed our SMCI, SPCX, MRNA, ETH, SOL, and AAVE longs in profit, and played the downside through a medium-term short in BE, with profits now locked in on 75% of the position.
We are now watching high-quality names near support zones for the first signs of buyers stepping back in. Selloff weeks like this clearly reveal the next market leaders, though we always wait for price confirmation first.
All closed trades are published openly on the BelFed website.
We've already mapped entries on the tickers in this report.
Levels, stops, and targets live inside the members area and Telegram, pushed the moment a setup triggers. Start a 14-day trial and get access before we open the first position in this theme. No card required.